
Blogs
PW Consulting: Water Softeners Market to Reach $5,244M by 2032 at 6.85% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence in the Global Water Softeners Market: Navigating Growth and Consolidation Through 2032
Executive Overview
Hard water remains a persistent challenge across residential, commercial, and industrial sectors, driving sustained demand for reliable softening solutions. As infrastructure ages, regulatory standards tighten, and end-user awareness of scale prevention and appliance longevity improves, the water softeners market has entered a phase of structural expansion. Our latest market research publication maps this trajectory with granular precision, offering decision-makers a clear lens into revenue flows, technological shifts, and competitive positioning. The study spans historical performance from 2020 through 2025 and extends a forward-looking forecast window from 2026 to 2032, anchored in a base year of 2025. By translating macro-level momentum into actionable strategic guidance, this intelligence serves as a critical reference point for capital allocation, product development, channel strategy, and partnership evaluation.
The market has demonstrated consistent upward movement over the past five years, with total revenue climbing from approximately 2500 million USD in 2020 to 3310 million USD in 2025. This growth trajectory reflects a combination of rising household penetration, industrial water treatment mandates, and renewed commercial facility upgrades. The forecast period projects continued expansion, with market valuation expected to reach 3649.48 million USD in 2026 and advance steadily toward 5244.0 million USD by 2032. Underlying this progression is a forecast CAGR of 6.85%, a rate that signals durable demand rather than transient spikes. For executives planning multi-year initiatives, this growth curve provides a reliable scaffold for scenario modeling, capacity planning, and market entry timing.
Growth Trajectory and Structural Drivers
The sustained expansion observed between 2020 and 2025 was not accidental. It emerged from a convergence of consumer priorities, operational cost pressures, and regional infrastructure modernization. As water quality concerns gained prominence, end-users increasingly recognized the long-term economic benefits of hardness mitigation, including reduced scale buildup, extended equipment lifespans, and improved cleaning efficiency. Residential adoption benefited from heightened awareness of household appliance protection and wellness-oriented purchasing behavior. Commercial operators integrated softening systems into facility management programs to stabilize maintenance costs and ensure consistent water quality across hospitality, healthcare, and multi-unit residential properties. Industrial users, meanwhile, continued to prioritize water treatment as a component of process reliability and compliance management.
Water Hardness Removal Market
Looking ahead to the 2026–2032 forecast window, several structural catalysts will shape the pace and composition of demand. Technological refinement in resin performance, brine management, and system automation is lowering total cost of ownership while improving user experience. Energy-conscious designs are aligning softening equipment with broader sustainability agendas, making water treatment investments more compatible with corporate environmental targets. Channel evolution is also accelerating, as direct-to-consumer models, specialized dealer networks, and integrated plumbing partnerships reshape how systems are specified, installed, and serviced. These dynamics create a market environment where growth is not merely a function of unit volume but also of value-added service, differentiation, and lifecycle management.
Forecast Window and Decision-Making Implications
The 2026–2032 forecast period is particularly significant for enterprises weighing expansion, product refresh cycles, or geographic diversification. The projected escalation from 3649.48 million USD in 2026 to 5244.0 million USD by 2032 underscores a market that is broadening in both scale and complexity. For manufacturers, this implies the need to balance volume growth with margin protection, especially as competitive intensity increases and consumer expectations around efficiency and ease of maintenance rise. For distributors and service providers, the forecast highlights opportunities in installation scale, remote monitoring, and preventive maintenance contracts. For investors and corporate development teams, the trajectory points to a sector where consolidation, brand positioning, and technology differentiation will increasingly determine which participants capture disproportionate share.
Strategic planning in this environment requires more than headline figures. Decision-makers need visibility into how demand fragments across application contexts, how system types evolve in response to regulatory and consumer preferences, and how regional markets diverge in purchasing behavior, infrastructure readiness, and competitive saturation. Our research is structured to deliver this multi-dimensional view without overwhelming stakeholders with undifferentiated data dumps. Instead, the report organizes findings around operational questions: where should new capacity be directed, which product architectures align with durable demand, and how should channel investments be prioritized to maximize return in a maturing landscape?
Competitive Landscape and Strategic Positioning
The market’s growth trajectory unfolds against a backdrop of concentrated yet dynamic competition. Aggregate market structure indicates meaningful consolidation, with the top three participants collectively accounting for approximately 65.4% of revenue and the top five reaching around 78.2%. This concentration signals that scale, brand equity, distribution reach, and service infrastructure remain decisive advantages. At the same time, differentiation is intensifying as companies compete on system architecture, ease of installation, certification claims, and residential or commercial-specific feature sets.
Several established players illustrate the strategic diversity shaping the sector. Culligan International, headquartered in Illinois, maintains a broad residential and commercial presence built around cation exchange resin technology for hardness reduction, leveraging a well-recognized brand and extensive service networks. A.O. Smith Corporation, based in Milwaukee, Wisconsin, focuses on residential PRO water softeners with energy-efficient single-tank designs, aligning product development with efficiency-conscious consumer expectations. Kinetico Incorporated, operating from Newbury, Ohio, differentiates through non-electric water softeners certified for reducing calcium and magnesium deposits, appealing to customers seeking mechanically robust, low-maintenance solutions. Hellenbrand, located in Waunakee, Wisconsin, supplies both residential and commercial systems, including the ProMate EcoMax series, reflecting a portfolio strategy that spans application segments while emphasizing performance and efficiency.
These profiles are not merely company summaries; they reveal how incumbents position themselves across the value chain. Some compete primarily on brand trust and service density. Others prioritize engineering trade-offs such as energy consumption, electrical dependency, or installation simplicity. Together, they define the competitive benchmarks against which new entrants, regional challengers, and product innovators must calibrate their strategies. The report examines these positioning patterns in detail, mapping how product portfolios, channel structures, and regional footprints interact to shape share dynamics and barrier-to-entry conditions.
Report Architecture and Operational Utility
This market research publication is designed for practical application rather than passive reference. It combines macro-level market sizing with structured segmentation analysis, allowing stakeholders to trace how overall revenue translates into distinct market pathways. The report examines the market by region, by type, and by application, providing a layered view of where demand concentrates, how system preferences diverge, and which segments exhibit the strongest momentum. Rather than presenting isolated percentages or fixed monetary values for each segment, the analysis emphasizes relative scale, ordering, and strategic context so that readers can interpret where opportunities and risks are most pronounced.
The study also integrates competitive profiling, market concentration metrics, and forward-looking scenario considerations to support strategic decision-making. Readers will find structured evaluations of how leading companies position their offerings, where service and distribution capabilities matter most, and which product categories are likely to see the most intense innovation pressure. The report further addresses the operational implications of market evolution, including installation and maintenance workflows, customer retention levers, and the role of certifications and performance claims in purchasing decisions.
Water Softeners Market
By organizing intelligence around both market structure and competitive behavior, the publication enables users to quickly narrow in on the questions most relevant to their function. Executives can use the findings to inform portfolio priorities and geographic focus. Product leaders can assess architectural trends and differentiate against established designs. Sales and channel teams can align go-to-market efforts with demand patterns and regional readiness. Corporate development teams can evaluate partnership targets, acquisition rationale, and consolidation pathways within a clearly defined concentration framework.
Strategic Takeaways for 2026 Planning
As organizations finalize 2026 strategies, the water softeners market presents a landscape defined by steady expansion, concentrated competition, and increasing emphasis on efficiency, service, and differentiation. Several strategic priorities emerge from this environment. First, growth planning should account for the market’s move from early adoption momentum toward more mature, service-driven demand patterns, where installation quality, maintenance reliability, and system longevity increasingly influence repeat purchasing and referrals. Second, competitive positioning will depend on clarity of product architecture and the ability to communicate tangible benefits around scale prevention, energy use, and operational convenience. Third, channel strategy must be calibrated to regional demand behavior and to the preferences of end-users who value either integrated service relationships or streamlined purchasing experiences.
The forecast period also implies that market participants will need to manage the tension between volume growth and margin discipline. As demand broadens and competition sharpens, pricing pressure may intensify in certain segments, making value-added services, differentiated features, and efficient supply chain execution essential to sustained profitability. Leaders should also monitor how certification standards, consumer education, and regulatory expectations evolve, since these factors can accelerate adoption in some contexts while reshaping specification requirements in others.
Conclusion
The global water softeners market is advancing along a clear growth path, supported by durable demand drivers and a competitive environment where scale and differentiation both matter. The 2026–2032 forecast window offers a practical planning horizon for organizations seeking to align product strategy, channel investments, and expansion decisions with market reality. Our full research publication expands on the macro trends outlined here, providing detailed segmentation analysis, competitive profiling, regional context, and forward-looking strategic guidance that together form a comprehensive decision-support toolkit.
To access the complete dataset, segment-level evaluation, company positioning detail, and scenario-ready market projections, we invite leaders to review the full Water Softeners Market report. The complete intelligence package is structured to support both immediate 2026 planning and multi-year strategic commitments, giving stakeholders the clarity required to act with confidence in a growing but increasingly competitive market.
For detailed analysis of this topic, please visit the official page: Water Softeners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cloud Accounting Market Hits $2.6B in 2025, Projects 7.8% CAGR Through 2032
By pmarketresearch, 2026-09-15
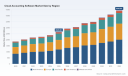
Strategic Intelligence for the 2026 Decision-Maker: Why the Cloud Accounting Software Market Research Matters Now
The shift from on-premise ledgers to cloud-native financial ecosystems is no longer a question of if, but how fast and how intelligently enterprises can execute. As we move through 2026, finance leaders, procurement directors, and technology strategists are grappling with a market that has matured beyond simple digitization. It is now a competitive arena defined by AI-driven automation, regulatory tightening, and subscription economics that treat financial infrastructure as a continuous service rather than a one-time capital expenditure. PW Consulting has just released a comprehensive market research study on the Cloud Accounting Software landscape, and this overview outlines why the findings should be central to your 2026–2032 planning cycle.
Online Accounting Software Market
This research is not a static snapshot. It spans historical tracking from 2020 through 2025 and extends a six-year forecast horizon to 2032, giving decision-makers a longitudinal view of adoption curves, pricing shifts, and competitive repositioning. The overarching trajectory points to a compound annual growth rate of 7.8 percent, a figure that reflects sustained enterprise demand, expansion within small and mid-sized segments, and the accelerating migration away from legacy desktop systems. Total revenue measured in US dollars has grown from approximately 1,863 million in 2020 to roughly 2,645 million by 2025, and the forward curve projects continued expansion toward 4,440 million by 2032. These numbers are not just indicators of a healthy market; they are signals of structural change in how organizations manage cash flow, compliance, reporting, and financial collaboration.
Cloud Accounting Software Market
For 2026 decision-makers, the strategic value of this study lies in its ability to translate macro momentum into actionable positioning. The forecast period captures a window where platform differentiation is increasingly driven by embedded analytics, real-time bank connectivity, and ecosystem partnerships rather than core ledger functionality alone. Procurement teams can use the analysis to evaluate subscription models that align cost with actual usage, while finance transformation offices can leverage the competitive mapping to understand where consolidation pressure is building and where niche players are carving defensible territory. The research is structured to help executives move from broad market awareness to precise vendor evaluation, investment prioritization, and risk mitigation.
What the Report Delivers: From Market Architecture to Execution Playbooks
This study is designed as an operational intelligence asset, not a descriptive summary. It unpacks the cloud accounting software market across multiple dimensions so that strategy, product, and finance leaders can pressure-test their assumptions against documented trends and forward-looking scenarios. The analytical framework covers market sizing, segmentation behavior, concentration dynamics, regulatory catalysts, and the strategic moves of leading vendors. Each section is written with the explicit goal of supporting decision-making in budgeting, vendor selection, partnership evaluation, and internal capability roadmapping.
Readers will find a detailed breakdown of how the market is structured across deployment and service models, including the dominance of SaaS-oriented delivery and the continued role of alternative licensing arrangements. The report examines how organizations of different scales are absorbing cloud accounting tools, with particular attention to how small and mid-sized enterprises are driving volume growth while larger enterprises are expanding their footprint through ERP-integrated financial modules. Regional performance is also mapped, highlighting where adoption is most advanced, where growth is accelerating, and what local compliance or data-residency considerations are shaping deployment choices. These structural insights are essential for anyone allocating budget across geographies or deciding whether to standardize globally or adapt locally.
Beyond segmentation, the research provides a rigorously documented competitive landscape. It profiles the companies that are defining product direction, pricing strategy, and ecosystem integration in cloud accounting. The analysis goes beyond feature checklists to evaluate how each player is positioning against substitutes, where they are leaning into automation and advisory capabilities, and how recent corporate actions are reshaping the market’s center of gravity. This section is especially valuable for procurement and vendor management teams that need to understand not just what a platform can do today, but how a vendor’s roadmap and partnerships may alter total cost of ownership, integration burden, and long-term strategic fit.
The report also integrates the operational realities that influence adoption and retention. These include pay-as-you-go subscription dynamics that reduce upfront licensing friction, the importance of regional data storage options in meeting evolving privacy expectations, and the growing necessity of real-time regulatory monitoring to avoid compounding compliance penalties. By connecting market behavior with practical operational levers, the study helps leaders evaluate cloud accounting investments through a total-value lens rather than a narrow price-per-user comparison.
Competitive Landscape: Who Is Shaping the Market and How
The cloud accounting software space is defined by a concentrated group of incumbents and a long tail of specialized challengers. The research highlights a market environment in which the top three players account for roughly 58.5 percent of revenue and the top five extend that share to about 72.4 percent. This level of concentration indicates that scale, brand trust, and ecosystem breadth still matter enormously, but it also leaves meaningful room for differentiated offerings in specific segments, regions, and use cases. Understanding this concentration dynamic is critical for 2026 planning, because it informs both bargaining power in procurement negotiations and the likelihood of platform consolidation.
Several established vendors anchor the market with distinct strategic identities. Intuit continues to leverage QuickBooks Online as a leading cloud accounting solution for small to mid-sized businesses, with a strong emphasis on automated invoicing, expense tracking, and AI-powered insights. Xero has built its position around a cloud-native platform for small businesses and accounting firms, focusing on real-time collaboration, bank feeds, and invoice automation. Sage offers a broader range of options through Sage 50 Cloud and Sage Intacct, extending from small business accounting to enterprise-grade finance management, including budgeting, inventory, and compliance tools. Oracle remains relevant through Oracle NetSuite, which serves mid-market to large enterprise customers with ERP-integrated cloud accounting, advanced reporting, and inventory capabilities. These four names illustrate the breadth of the incumbent base and the different ways vendors are approaching scale, verticalization, and platform integration.
The competitive field also includes vendors with sharp positioning in specific audiences or geographies. FreshBooks is tailored to service-based small businesses, combining invoicing, time tracking, and client portals in a cloud-based workflow. Zoho Books targets startups and small teams with affordable cloud accounting that integrates CRM, inventory management, and multi-currency support. Wave provides a free-to-start entry point for microbusinesses, offering invoicing, expense tracking, and payroll integration as an accessible on-ramp to digital finance. Acumatica positions itself as a cloud ERP accounting platform for growing mid-sized businesses, adding supply chain and financial management depth. MYOB remains closely associated with small to medium businesses in Australia and New Zealand, emphasizing localized tax and compliance features. Together, these profiles demonstrate that cloud accounting is not a one-size market; it is a layered ecosystem where vendor fit depends heavily on company size, industry, geography, and operational complexity.
Recent corporate actions further illustrate how competition is intensifying around analytics, automation, and ecosystem reach. In March 2025, Intuit launched QuickBooks Cloud Plus with advanced AI-driven analytics for real-time financial insights and automated compliance alerts, signaling a push toward advisory-grade functionality. In February 2025, Xero acquired Fathom, a financial analysis and reporting platform, to strengthen its analytics and value-added services. Later in 2025, Xero partnered with Stripe to embed payables and receivables automation inside the accounting platform for faster cash flow, illustrating a broader trend toward embedded financial operations. In April 2025, Sage partnered with Microsoft Azure to develop a hybrid cloud accounting platform for large enterprises, highlighting the continuing relevance of infrastructure partnerships in enterprise deployments. These moves matter because they show vendors competing not only on core ledger accuracy but also on the speed, intelligence, and integration depth that finance teams increasingly expect.
Market Dynamics: Regulations, Economics, and the 2026 Compliance Imperative
Strategic planning for cloud accounting in 2026 cannot be separated from the regulatory and economic environment shaping deployment decisions. One of the most consequential developments is the AML/CTF Tranche 2 requirement, effective from July 2026, which requires accounting firms to implement demonstrable access controls for data privacy compliance in cloud accounting platforms. This creates a tangible compliance burden that interacts directly with vendor selection, because access control capabilities, auditability, and role-based permissions are becoming procurement criteria rather than optional features. For firms operating across multiple entities or jurisdictions, the ability to prove control maturity is now part of the operational contract with any cloud financial system.
Accounting standards are also evolving in ways that affect how organizations assess and expense cloud-based financial technology. ASU 2025-06, effective for fiscal years beginning after December 15, 2027, modernizes accounting for internal-use software to align with agile development practices. While this change is not limited to cloud accounting, it influences how enterprises treat implementation, customization, and continuous improvement investments in cloud financial systems. Decision-makers should anticipate that capital-versus-expense treatment, internal reporting, and project governance may shift as organizations adopt more iterative deployment models rather than large, fixed-scope implementations.
Beyond regulation, the economic structure of cloud accounting continues to reshape how organizations justify adoption. Pay-as-you-go subscription models reduce upfront licensing fees and align costs with actual usage, which is especially attractive for small businesses that need predictable cash flow management. At the same time, the stakes of non-compliance are rising in practical terms. Sales tax compliance in cloud accounting requires real-time regulatory monitoring across jurisdictions to avoid average annual penalty costs that can reach approximately 47,000 dollars. This figure underscores why automation, jurisdiction-aware rule sets, and strong integration with transaction data are becoming central value drivers rather than peripheral conveniences.
Data privacy considerations add another layer of complexity. Cloud accounting platforms increasingly offer data storage options within the United States or Europe to support evolving global privacy laws and compliance expectations. For multinational organizations and service providers handling client data, these options are not just technical details; they are enablers of trust, audit readiness, and cross-border operational continuity. The 2026 planner must therefore evaluate cloud accounting solutions not only on functionality and price, but also on where data resides, how access is governed, and how quickly the platform can adapt to new regulatory requirements.
Why This Research Should Anchor Your 2026 Strategy
The Cloud Accounting Software Market research is built for leaders who need to convert market momentum into informed decisions. It provides the structural context to understand where growth is coming from, the competitive intelligence to evaluate vendor stability and differentiation, and the operational framing to connect platforms with compliance, cost, and data governance requirements. In a market moving at a 7.8 percent compound annual growth pace and approaching nearly 4.4 billion dollars by 2032, the margin between reactive procurement and strategic deployment is widening. Organizations that map their cloud accounting decisions to documented market behavior will be better positioned to manage risk, control total cost of ownership, and align financial systems with broader transformation goals.
The full report goes further than this overview can. It contains the detailed segmentation analysis, regional performance patterns, application-level adoption behavior, and vendor-by-vendor strategic assessments that executives need to justify investment, negotiate with vendors, and prioritize implementation roadmaps. If you are planning cloud accounting adoption, renewal, replacement, or integration in 2026, this study is designed to serve as a decision-grade reference rather than a high-level introduction.
To access the complete market sizing, forecasting tables, competitive profiles, and the full set of dynamics shaping the next six years, visit the source page for the PW Consulting Cloud Accounting Software Market research. The full intelligence package is available there for teams that need to move from strategic awareness to execution-ready clarity.
For detailed analysis of this topic, please visit the official page: Cloud Accounting Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Contact Lens Solution Market Hits $2.2B in 2025, Nears $2.9B by 2032
By pmarketresearch, 2026-09-15
Strategic Horizons 2026: Navigating Growth and Consolidation in the Global Contact Lens Solution Market
Executive Preview
The contact lens solution market stands at a pivotal juncture as we move through 2026, characterized by steady quantitative expansion and an increasingly complex competitive architecture. Recent comprehensive analysis from PW Consulting indicates that the global market, estimated at USD 2,200 Million in 2025, is projected to reach approximately USD 2,900 Million by 2032. This trajectory reflects a compound annual growth rate of 4.5 percent over the forecast period, signaling a resilient industry ecosystem that continues to attract strategic investment despite macroeconomic headwinds and evolving regulatory frameworks.
For executives, product managers, and commercial strategists, these aggregate figures represent more than baseline growth. They encapsulate shifting consumer preferences, the maturation of silicone hydrogel adoption, persistent emphasis on ocular health and hygiene, and the strategic importance of formulation innovation. The current market landscape is shaped by a historical progression from USD 1,850.0 Million in 2020 through successive annual expansions, reaching USD 2,104.55 Million in 2024 and crossing the USD 2,200.0 Million threshold in 2025. This consistent upward momentum provides a reliable foundation for demand forecasting, capacity planning, and portfolio optimization.
Our freshly published Contact Lens Solution Market research offers an actionable, data-rich roadmap tailored for 2026 decision-making. It moves beyond surface-level narratives to deliver granular demand patterns, competitive benchmarking, regulatory touchpoints, and scenario-based projections that enable organizations to align their go-to-market strategies with realistic commercial pathways. The following overview highlights the strategic architecture of the study while preserving the detailed segmentation intelligence that readers can access through the complete report.
Macro Trajectory and Forecasting Architecture
The projected growth pattern from 2026 through 2032 illustrates a market that is expanding in size while simultaneously experiencing subtle cyclical adjustments and regional recalibration. Following the 2025 baseline of USD 2,200.0 Million, the forecast indicates market expansion to approximately USD 2,324.99 Million in 2026, advancing to USD 2,476.25 Million in 2027 and USD 2,579.58 Million in 2028. A modest consolidation phase appears around 2029, with values stabilizing near USD 2,558.63 Million before resuming growth toward USD 2,682.82 Million in 2030, USD 2,728.37 Million in 2031, and the terminal forecast figure of USD 2,900.0 Million in 2032.
This ebb-and-flow structure is not an anomaly; it reflects the integration of demand saturation in mature channels, distribution recalibration, product cycle timing, and the lag effects of regulatory or raw material fluctuations. Decision-makers who rely on linear extrapolations risk misallocating resources or underestimating the strategic value of timing-specific interventions. Our forecasting framework incorporates historical continuity from 2020 through 2025, ensuring that short-term operational plans are anchored in empirically observed performance rather than speculative optimism.
Strategic Segmentation and Commercial Implications
A central pillar of this research is its segmentation architecture, which enables companies to isolate high-potential avenues without losing sight of the broader market system. The analysis evaluates demand distribution across application types, formulation categories, and geographical footprint, offering a structured lens through which to prioritize product development, sales force deployment, and packaging strategy.
Within application-driven demand, the study examines how rinsing, cleaning, and disinfecting functions interact with lens material evolution, wearer compliance behavior, and professional recommendations from optometrists and ophthalmologists. Rather than presenting static percentages, the report explores the relative commercial weight of each function, the operational implications for manufacturing and fill-finish processes, and the consumer education dynamics that influence repeat purchase frequency. These insights are critical for organizations seeking to position formulations that balance convenience with clinical trust.
The type-based evaluation provides a parallel view of competitive differentiation across multi-purpose systems, hydrogen peroxide-based formulations, and complementary categories. Each type carries distinct value propositions, stability considerations, packaging constraints, and user-experience expectations. By examining how these categories perform in practical usage environments and how they align with evolving lens material compatibility, the research helps stakeholders determine where incremental innovation can generate disproportionate returns and where commoditization risks may require defensive pricing or service-based differentiation.
Geographically, the report maps the global landscape through a functional distribution lens that highlights the operational characteristics of major regional markets. Instead of reducing complex trade dynamics to simplistic regional rankings, the analysis explores market penetration patterns, channel maturity, retail and pharmacy influence, and the role of local regulatory expectations in shaping product availability. This enables enterprises to identify where near-term volume capture is achievable versus where longer-term brand-building and distribution partnership strategies will yield more sustainable outcomes.
Competitive Dynamics and Enterprise Positioning
The contact lens solution sector remains notably concentrated, with the top three enterprises collectively representing approximately 65 percent of market revenue and the top five firms accounting for around 75 percent. Such concentration intensifies the strategic stakes for both incumbents and challengers. Established players must defend share through continuous formulation enhancement, brand reinforcement, and channel efficiency, while emerging or niche participants need clear differentiation vectors to gain retailer trust and professional endorsement.
Contact Lenses Market
The competitive landscape examined in this study features organizations with distinct operational identities and strategic priorities. Bausch + Lomb Incorporated, headquartered in Rochester, NY, maintains a strong presence through its multi-purpose portfolios, emphasizing hydration, cleaning, and disinfection attributes that align with mainstream wearer routines. Alcon Inc., based in Fort Worth, TX, leverages its solution lines to address disinfection performance, protein removal, and all-day comfort, reinforcing clinical credibility alongside consumer convenience. CooperVision, Inc., operating from New York, NY, supports both soft and rigid lens care through multipurpose and peroxide system offerings, reflecting the importance of lens-type compatibility in product strategy.
International players contribute further dimensionality to the market structure. Menicon Co., Ltd., located in Nagoya, Japan, supports silicone hydrogel and rigid gas permeable lens ecosystems, highlighting the importance of material-specific formulation expertise. Contamac Holdings Limited, based in London, UK, specializes in lens materials and multipurpose or peroxide solutions for GP, scleral, and hybrid lenses, positioning itself within specialized care segments. Oté Pharma Sol B.V., from Uden, Netherlands, emphasizes preservative-free and peroxide-based options for soft and RGP lenses, reflecting demand for gentler formulation profiles. OPHTECS Corp., headquartered in Tokyo, Japan, advances innovative care solutions that span multipurpose and specialized formulations, underscoring the continued relevance of product differentiation in a crowded category.
Beyond the incumbents, recent industry activity illustrates how regulatory milestones and product innovation continuously reshape commercial expectations. In December 2025, Bruno Vision Care LLC received FDA clearance for the first EDOF daily disposable contact lens incorporating extended depth of focus optics. While this development directly concerns lens hardware, it signals broader momentum in vision correction technology and reinforces the strategic interdependence between lens design, wearer demographics, and care solution requirements. As lens formats evolve, solution providers must anticipate compatibility demands, consumer education needs, and packaging or instructional adjustments.
Regulatory, Raw Material, and Reimbursement Considerations
Market performance in this category is heavily mediated by regulatory expectations, formulation governance, and reimbursement accessibility. Contact lens solutions are regulated as Class II FDA devices, requiring 510(k) clearance and sterility testing per USP <71>. Compliance with 21 CFR § 800.12 for tamper-resistant packaging and labeling adds another operational layer, while any significant design or formulation change triggers the need for updated 510(k) notifications. These requirements shape development timelines, cost structures, and the agility with which companies can launch iterative improvements.
Formulation integrity also depends on the careful selection and control of standard ingredients such as preservatives, wetting agents, disinfectants, and humectants. These components must ensure sterility, compatibility with diverse lens materials, and consistent user experience. Supply chain resilience, vendor qualification, and quality assurance protocols therefore become strategic assets rather than routine procurement matters. Any disruption in raw material availability or qualification standards can affect fill rates, regional availability, and time-to-market for reformulated offerings.
On the consumer side, reimbursement accessibility through Health FSA and FSA accounts when purchased for vision care treatment influences purchase behavior and channel selection. This financial mechanism can enhance affordability and encourage consistent replenishment, particularly in markets where out-of-pocket sensitivity is high. However, it also requires clear documentation, retail enrollment support, and consumer communication strategies that convert reimbursement eligibility into tangible repeat purchase behavior. The study incorporates these factors into a broader examination of demand durability and channel economics.
Contact Lens Solution Market
Report Contents and Decision-Ready Framework
The complete report is designed to support cross-functional planning with practical, implementation-focused content. It provides:
- A full market size and forecast model spanning the historical period and the 2026-2032 outlook, structured for scenario testing and revenue planning
- Segment-level evaluation across application functions, formulation types, and regional distribution patterns to guide portfolio prioritization
- Competitive profiling of key market participants, with attention to product architectures, strategic emphasis, and positioning logic
- Analysis of regulatory requirements, formulation ingredients, packaging constraints, and reimbursement dynamics that affect commercial execution
- Exploration of demand drivers, distribution channel behavior, professional endorsement influence, and consumer compliance patterns
- Identification of near-term opportunities and risk factors that can affect production planning, pricing strategy, and market entry timing
To maintain the depth and integrity of the analysis, detailed regional values, application-level revenue breakdowns, and type-specific market shares are provided within the full report rather than in this overview. This approach preserves the strategic narrative while ensuring that precise figures remain accessible to stakeholders who require them for internal modeling, investment justification, and operational planning.
Strategic Takeaways for 2026
As organizations prepare for the remainder of 2026 and look toward the end of the decade, several strategic imperatives emerge from the market structure. First, growth is real but must be managed with discipline, given the concentration of revenue among leading firms and the cyclical nature of the forecast curve. Second, differentiation increasingly depends on formulation credibility, lens compatibility, packaging reliability, and consumer education rather than price competition alone. Third, regulatory compliance and quality assurance are not overhead items but core strategic capabilities that influence speed, cost, and market access. Fourth, reimbursement frameworks and channel dynamics can materially affect repeat purchase behavior and should be integrated into commercial planning.
The Contact Lens Solution Market research from PW Consulting equips leaders with the intelligence required to navigate these complexities. By combining historical continuity, forecast discipline, segmentation clarity, and competitive context, the study supports more confident decisions around product focus, geographic prioritization, partner selection, and capacity alignment. The full report contains the precise figures, segmentation resolution, and comparative detail needed for rigorous internal analysis and executive-level strategy development.
For detailed analysis of this topic, please visit the official page: Contact Lens Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fire Doors Market Hits $12,180 Million in 2025, Projects 4.2% CAGR Through 2032
By pmarketresearch, 2026-09-15
Navigating Safety and Growth: Strategic Imperatives in the Global Fire Doors Market (2026–2032)
In an era where regulatory scrutiny and asset protection converge, the fire doors market has evolved from a passive compliance expenditure into a dynamic strategic asset class for facility owners, contractors, and investors. As organizations across commercial, residential, industrial, healthcare, and educational sectors reassess their life-safety infrastructure, understanding the nuanced trajectory of this segment is critical for capital allocation and risk management in 2026 and beyond.
PW Consulting’s latest comprehensive analysis of the Fire Doors Market provides decision-makers with the granular intelligence required to navigate this complex landscape. This article outlines the high-level market trajectory, the shifting dynamics driven by regulation and material innovation, and the competitive maneuvers shaping the industry. It serves as a strategic primer to the full report, which offers exhaustive segmentation, detailed company profiling, and forward-looking scenario analysis essential for formulating robust market entry, procurement, and investment strategies.
The Macro Trajectory: Sustained Growth Anchored by Safety Mandates
The global market for fire doors has demonstrated consistent resilience and expansion over the past five years. Valued at approximately USD 9.88 billion in 2020, the market has grown steadily to reach an estimated USD 12.18 billion by 2025. This historical progression reflects not only the recovery from broader economic fluctuations but also the compounding effect of stricter building codes, urbanization trends, and heightened awareness of fire safety in both new construction and retrofit projects.
Looking ahead, the forecast period from 2026 to 2032 signals continued upward momentum. The market is projected to surpass the USD 12.9 billion mark in 2026, with growth accelerating through the latter half of the decade. By 2032, the total market revenue is anticipated to approach USD 16.06 billion. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 4.2% over the forecast horizon.
Important Note: These aggregate figures mask significant variability across materials, applications, and geographies. The full report dissects these variables to reveal which specific sub-segments are outperforming, where saturation risks lie, and how regional regulatory environments are skewing demand. Relying on top-line numbers alone can lead to misallocated capital; sector-specific intelligence is paramount.
Market Dynamics: Regulation, Technology, and Supply Chain Realignment
Regulatory Evolution as a Primary Demand Driver
The regulatory landscape is undergoing a transformative shift, fundamentally altering how fire door assemblies are specified, installed, and maintained. The 2025 edition of NFPA 80, Standard for Fire Doors and Other Opening Protectives, has introduced rigorous requirements that extend beyond initial installation. It mandates immediate inspection following installation and a minimum annual inspection cycle thereafter. Furthermore, the introduction of performance-based inspection, testing, and maintenance options under Annex J provides facility managers with flexibility but also demands higher levels of documentation and technical competency.
In parallel, regional certification mandates are tightening. In India, the Bureau of Indian Standards (BIS) Quality Control Order (QCO) and IS 3614:2021 certification have become mandatory for wooden and metal fire doors sold in the market starting in 2025. This shift is reshaping procurement strategies for stakeholders operating in South Asia, forcing a re-evaluation of supply chains and approved vendor lists.
Additionally, upcoming revisions to UL 10C, effective 2026, will enhance security and resistance requirements for locks and latches on fire-rated door assemblies. This convergence of fire safety and security standards is creating new integration challenges and opportunities for manufacturers who can deliver holistic solutions.
The Shift Toward Full-System Certification
The industry is moving decisively away from component-level assumptions toward full-assembly certification. Fire door assemblies must now be tested as complete systems, including the door leaf, frame, hardware, seals, and glazing, under ISO/IEC 17025 accredited full-assembly testing protocols. This trend raises the barrier to entry for smaller players and favors integrated solution providers. It also compels procurement teams to scrutinize not just the door leaf, but the entire ecosystem of hardware and installation protocols to ensure compliance and liability protection.
Material and Application Nuances
While metal continues to dominate the material mix due to its durability, fire resistance ratings, and suitability for commercial applications, the market is witnessing nuanced shifts. Timber and wood remain significant, particularly in residential and design-focused commercial projects, while glass fire doors are carving out specialized roles in healthcare and luxury commercial spaces where visibility and aesthetics are paramount.
Applications distribution reveals that commercial buildings represent the largest demand pool, driven by high-density occupancy and stringent code enforcement. Residential buildings follow as a substantial contributor, fueled by urbanization and multi-family housing developments. Industrial facilities, healthcare facilities, and educational facilities constitute vital specialized segments, each with unique performance requirements regarding hygiene, acoustic control, hazardous material handling, and durability under heavy use.
Important Note: The report provides a detailed breakdown of material and application splits, quantifying the exact revenue contributions and growth rates for each category. It also highlights which applications are experiencing the fastest adoption of specific materials and the strategic implications of these trends for suppliers. Do not rely on generalized assumptions about market mix; the detailed segmentation analysis exposes hidden opportunities and competitive vulnerabilities.
Security Door Market
Competitive Landscape: Consolidation and Differentiation
The fire doors market is characterized by a fragmented but strategically active competitive environment. While market concentration metrics indicate that the top three players hold a modest share and the top five maintain a slightly higher aggregate presence, the landscape is defined by intense competition between global giants, regional specialists, and manufacturers leveraging geographic advantages.
Key Players and Strategic Maneuvers
Leading multinational corporations continue to solidify their positions through acquisitions and product innovation. ASSA ABLOY, headquartered in Sweden, provides fire-rated doors, frames, and integrated door systems with UL-listed fire protection offerings tailored for commercial and institutional applications. In April 2025, ASSA ABLOY acquired Door System, a Danish manufacturer of fire-rated doors serving pharmaceutical, food, and retail sectors, signaling a strategic push into specialized hygiene and high-traffic environments.
Dormakaba, based in Switzerland, manufactures fire-rated doors, frames, and low-energy door assistants certified to UL and international standards. At BAU 2025, Dormakaba introduced EasyAssist Pro, a low-energy door assistant for fire-rated doors, addressing the growing demand for accessibility and energy efficiency in building operations.
JELD-WEN, headquartered in the USA, offers fire-rated door systems including wood and metal doors listed for fire resistance under UL 10C and NFPA 252, maintaining a strong footprint in North America. Steelcraft, also a US-based manufacturer, specializes in fire-rated steel doors and frames rated up to 3 hours, compliant with UL 10C and NFPA 252 for commercial use, catering to high-performance requirements.
Republic Doors & Frames, another US player, produces fire-rated steel doors and frames with positive-pressure and zero-pressure ratings under UL 10C and NFPA 252, emphasizing versatility in pressurized environments. Allegion, with operations extending from Ireland to the US, supplies fire-rated doors, frames, and hardware assemblies certified to UL standards including UL 10C and NFPA 252. In February 2025, Allegion completed the acquisition of Lemaar, an Australian door hardware company specializing in entry systems for fire-rated doors, expanding its integrated hardware capabilities in the Asia-Pacific region.
SAFTI First stands out as a manufacturer of fire-rated glass and door systems with full-assembly certifications for UL-listed fire protection, offering unique value propositions in applications where glazing and fire resistance must coexist. Chace Industries produces fire-rated steel doors and frames for institutional and commercial markets under UL and NFPA standards, reinforcing the competitive density in North America.
European manufacturers are also active. Metaflex Doors, based in the Netherlands, supplies fire-rated doors and frames with European and international certifications including UL listings. GEZE, from Germany, provides fire-rated door systems and accessories with full-assembly testing for UL and NFPA compliance. The Lindner Group, a German manufacturer, produces fire-rated doors with German and international UL-listed fire resistance certifications. NINZ S.p.A., based in Italy, produces fire-rated doors and frames certified under European and UL standards. Agta record and Gilgen Door Systems, both Swiss manufacturers, contribute fire-rated doors and frames and systems respectively, certified to UL and European standards, leveraging the Swiss reputation for precision engineering.
In the United States, Ceco Door specializes in engineered steel fire-rated doors and frames for commercial and institutional projects, while AMBICO offers fire-rated and acoustic door systems with UL listings for hazardous and secure environments.
Emerging and Regional Contenders
Global reach is expanding through manufacturers in Asia and India. Sanwa Holdings, based in Japan, develops fire-rated doors with Japanese manufacturing precision and UL international certifications, positioning itself for export markets. Yuankai Door and Buyang Group, both from China, produce fire-rated doors and frames with UL and international listings for global markets. Buyang Group, as a large-scale producer, competes on volume and cost efficiency in the steel fire-rated door segment.
Godrej Security Solutions, based in India, offers fire-rated doors and security solutions with ISI and UL listings in India and international markets, aligning with the domestic regulatory push and export ambitions.
Important Note: The report contains exhaustive profiles of all these key companies, including strategic analysis, revenue implications of recent developments, competitive positioning maps, and detailed assessments of their product portfolios and geographic strengths. Understanding the specific moves of each competitor is essential for benchmarking, partnership evaluation, and threat assessment. The full analysis reveals which companies are gaining share, where capacity expansions are occurring, and how M&A activity is reshaping supply alliances.
Recent Developments: M&A and Standard Updates Reshaping the Field
The competitive dynamics are further influenced by recent strategic events. In December 2025, Investcorp completed the acquisition of Guardian Fire Services, a leading US provider of fire and life safety services including fire doors. This move underscores the growing interest in integrated service models that combine product supply with inspection, maintenance, and compliance management, particularly in light of the new annual inspection mandates under NFPA 80.
Meanwhile, the NFPA released the 2025 edition of NFPA 80 in March 2025, introducing updated inspection frequency and performance-based options. This regulatory update is expected to create immediate demand for inspection services and compliant hardware upgrades, influencing procurement cycles and vendor selection criteria across the industry.
Fire Doors Market
Important Note: The report evaluates the impact of these recent developments, including the financial and strategic ramifications of acquisitions, the market reception of new products like Dormakaba EasyAssist Pro, and the specific compliance challenges posed by the 2026 UL 10C revision. It also tracks upcoming trends and potential future catalysts. Without this forward-looking context, organizations risk being caught off-guard by supply chain shifts or regulatory non-compliance.
Regional Insights: Divergent Growth Patterns
Geographically, the market exhibits distinct growth paces and regulatory drivers. North America remains a mature but steady market, driven by retrofit activity, healthcare expansion, and compliance with updated NFPA standards. Europe continues to emphasize high-performance materials and integrated systems, with strong regional players leveraging European certifications alongside UL listings for global projects.
Asia Pacific stands out as a region of significant scale and dynamic growth, fueled by rapid urbanization, infrastructure development, and the implementation of local mandatory certification regimes such as BIS in India. Latin America and the Middle East and Africa are emerging as important markets, though they face unique challenges related to supply chain localization, certification harmonization, and varying levels of regulatory enforcement.
Important Note: The full report provides a detailed regional analysis, quantifying market sizes and growth trajectories for each region without relying on broad generalizations. It identifies key country-level opportunities, regulatory bottlenecks, and the competitive intensity within each geography. This regional granularity is critical for companies planning market entry, distributors seeking to optimize territory coverage, and investors assessing regional risk profiles.
Strategic Recommendations for 2026 Decision Makers
As the market moves toward projected valuation milestones and navigates evolving regulatory requirements, organizations must adopt a proactive rather than reactive stance. Strategic actions for 2026 should include:
- Audit Compliance Against 2025 NFPA 80 Updates: Facility managers and contractors must ensure that inspection protocols align with the immediate post-installation and annual inspection mandates, as well as explore performance-based options under Annex J where applicable. Non-compliance carries escalating liability risks.
- Evaluate Full-Assembly Certification: Procurement teams should prioritize vendors who can demonstrate ISO/IEC 17025 accredited full-assembly testing for the complete door, frame, hardware, and glazing system. This reduces integration risk and ensures that the performance rating applies to the installed configuration.
- Monitor Material and Application Trends: While metal remains a workhorse, understanding the specific growth pockets in timber, glass, and composite materials, and their alignment with particular applications like healthcare or residential, allows for targeted product development and marketing.
- Assess Supply Chain Exposure to Regional Mandates: With India enforcing mandatory BIS QCO and IS 3614:2021 certification, and UL 10C revisions impacting hardware in 2026, organizations must review vendor certifications and ensure continuity of supply for compliant components.
- Watch Competitive M&A Activity: The acquisition of Door System by ASSA ABLOY and Guardian Fire Services by Investcorp, along with Allegion’s move on Lemaar, signals consolidation and a push toward integrated service and hardware solutions. Organizations should assess how these moves affect pricing, availability, and the competitive landscape in their target segments.
- Leverage Granular Intelligence for Capital Allocation: The aggregate market size and CAGR provide a directional signal, but profitable decisions depend on knowing exactly which material-application-region combinations are driving the highest margins and fastest growth. The full PW Consulting report delivers this level of detail.
Conclusion: The Strategic Value of the Fire Doors Market Research
The global fire doors market stands at an inflection point where regulatory rigor, technological integration, and competitive consolidation are reshaping the value chain. For stakeholders in 2026, success will depend on more than just observing broad market growth; it requires deep, segmented intelligence that connects macroeconomic trends to actionable operational insights.
This overview has highlighted the market’s robust trajectory, the transformative impact of NFPA 80 and full-assembly testing, and the strategic moves of key global and regional players. However, to fully capitalize on these insights, decision-makers need access to the complete analytical framework provided in PW Consulting’s dedicated Fire Doors Market report.
Important Note: The comprehensive report goes far beyond these summaries. It delivers precise market size estimates and CAGR breakdowns for every material, application, and region. It provides detailed competitive profiling, including strategic analysis, SWOT evaluations, and supply chain assessments for each key company. It includes a thorough analysis of recent developments, their financial implications, and future outlooks. It also offers strategic recommendations tailored to specific stakeholder roles, from manufacturers to investors and facility operators.
For organizations committed to making informed, risk-adjusted decisions in the coming year, the full market research report is an indispensable tool. It transforms high-level trends into a navigable roadmap, exposing the hidden data points that separate strategic leaders from the competition. Access the complete intelligence to secure your competitive edge in the evolving fire doors landscape.
For detailed analysis of this topic, please visit the official page: Fire Doors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: All-Solid-State Battery Market Hits $9.69B in 2025, Forecasts 13.2% CAGR to $23.08B by 2032
By pmarketresearch, 2026-09-15
Navigating the All-Solid-State Battery Inflection Point: Strategic Intelligence for 2026 Decision-Makers
The global energy storage landscape is undergoing a structural transformation. As the industry moves beyond the mature lithium-ion paradigm, all-solid-state battery technology stands at a critical inflection point. The transition from laboratory validation to pilot production and early commercialization is no longer a theoretical horizon—it is actively reshaping competitive dynamics, supply chain architectures, and capital allocation strategies. For executives, investors, and policy stakeholders operating in 2026, understanding where the market stands, how it will compound, and which operational bottlenecks will dictate success is not optional. It is a prerequisite for informed decision-making.
This insight introduces PW Consulting's latest all-solid-state battery market research, a comprehensive analysis designed to translate complex technological trajectories into actionable strategic frameworks. The study is structured to support enterprise planning across technology roadmapping, regional expansion, partnership scouting, and risk mitigation. What follows is a demonstration of the analytical rigor embedded in the full report, alongside a clear outline of the operational intelligence it delivers.
The Trajectory: From Steady Base to Accelerated Scale
Historical data from 2020 through 2025 reveals a market that has consistently expanded, even as technological maturity and manufacturing readiness evolved at different paces across regions and developer categories. The baseline positioning in 2025 reflects aUSD-denominated market size that underscores both the growing commercial interest and the tangible progress in cell-level validation and early pilot lines. Looking forward, the forecast window spanning 2026 to 2032 projects a compound annual growth rate of 13.2 percent, with the market expected to surpass the ten-figure milestone in the near term and continue its upward compounding trajectory toward the end of the forecast period.
These macro-level figures are more than retrospective benchmarks. They signal the pace at which scaled adoption, OEM qualification cycles, and electrolyte supply chain maturation will converge. The growth curve implies that companies positioning themselves now—whether through proprietary cell architectures, electrolyte material scaling, or manufacturing partnerships—will face a market that rewards early alignment with gigawatt-scale production pathways and standardized testing protocols. The full research unpacks the drivers behind this trajectory, mapping the interplay between energy density breakthroughs, cost curve compression, and the gradual replacement of liquid electrolyte systems across priority application segments.
What the Report Delivers: Operational Intelligence Beyond Top-Line Numbers
PW Consulting's all-solid-state battery study is engineered for practitioners who must translate market signals into execution plans. The report goes beyond aggregated market sizing to provide a multi-dimensional operational lens. Core components include:
Solid State Batteries Market
- Technology segmentation mapping that dissects electrolyte material families, anode configurations, and cell architecture pathways, linking each technical route to manufacturing readiness, energy density ceilings, and cost structure implications.
- Application pathway analysis that evaluates demand evolution across electric mobility platforms, portable electronics, and specialized industrial use cases, highlighting qualification timelines, pack-level integration considerations, and difference in adoption pacing.
- Regional dynamics and deployment logic that contextualizes demand concentration, manufacturing footprint development, and policy environments without reducing complex ecosystems to static snapshots.
- Supply chain and infrastructure diagnostics that examine raw material throughput requirements, electrolyte production scaling challenges, roll-to-roll manufacturing economics, and the bottlenecks that will define early gigafactory execution.
- Competitive benchmarking and developer profiling that tracks active players across startup, joint venture, and incumbent OEM-affiliated models, with emphasis on pilot line status, sampling milestones, licensing strategies, and partnership ecosystems.
- Regulatory and standardization watchpoints that monitor evolving testing protocols, safety guideline development, and national standard releases that will influence certification pathways and market access timelines.
Each section is designed to support scenario planning. Readers will find structured comparisons that help evaluate which technical routes align with specific product roadmaps, which regional manufacturing ecosystems offer the most tractable scale-up pathways, and how developer types—from electrolyte material specialists to integrated cell manufacturers—are positioning for licensing, joint production, or standalone commercialization.
Competitive Landscape: Divergent Models, Converging Timelines
The all-solid-state battery ecosystem in 2026 is defined by a diversity of development models and a simultaneous push toward production readiness. The competitive field spans U.S.-based cell developers, electrolyte material suppliers, European joint ventures, Asian integrated manufacturers, and large incumbent players advancing pilot programs with targeted commercialization dates.
In the United States, several organizations are advancing parallel commercialization tracks. QuantumScape has operated with a clear focus on high-energy-density lithium-metal anodes paired with solid electrolyte architectures, and its recent inauguration of the Eagle Line automated pilot production facility in San Jose marks a transition toward OEM customer sampling and gigawatt-scale licensing. Nearby, Ampcera has concentrated on solid-state electrolyte materials, scaling sulfide electrolyte production in Tucson to support downstream cell development. Solid Power has pursued a sulfide-electrolyte route with multi-layer cell production on continuous roll-to-roll lines, targeting automotive OEM relationships that include BMW and Ford. These parallel tracks demonstrate how the U.S. ecosystem is differentiating between integrated cell development, material supply, and roll-to-roll manufacturing capabilities.
Europe's landscape reflects coordinated industrial ambition. Argylium, formed as a joint venture among Syensqo, Axens, and IFPEN, is focused on industrial production and commercialization of sulfide solid electrolytes, signaling a push to secure European electrolyte supply capacity. Meanwhile, ProLogium has advanced oxide ceramic electrolyte-based all-solid-state batteries with roll-to-roll manufacturing progress and gigafactory partnerships, including its collaboration with Mercedes-Benz Marseille. Ilika continues to develop all-solid-state technology with a pilot production focus for electric mobility applications, illustrating a more targeted approach to near-term validation.
In Asia, the pace of milestone achievement has accelerated. Greater Bay Technology, backed by GAC Group, rolled out its first A-sample cells using composite electrolytes, achieving energy density ranges that place it in a high-performance cohort and targeting GWh-scale mass production and vehicle installation. Samsung SDI is progressing with its SolidStack branding, targeting mass production in the second half of 2027 alongside partnerships for EVs and industrial applications. Toyota has received Japanese METI production approval and is targeting pilot production in 2026, leveraging a partnership with Idemitsu Kosan for mass-produced sulfide electrolytes. These developments underscore how Asian developers are compressing the timeline from cell validation to pilot and early mass-production planning.
The report profiles these and other active participants with structured operational summaries, tracking not only headquarters and public-facing positioning but also the concrete milestones that indicate where each organization sits on the commercialization curve. Recent events—such as automated pilot line inaugurations, A-sample cell rollouts, joint venture formations, and gigafactory partnerships—are integrated into a dynamic competitive map that helps readers assess who is moving from demonstration to deployment, and at what scale.
Market Dynamics: Standards, Funding, and Infrastructure Friction
The trajectory of all-solid-state battery commercialization is being shaped as much by regulatory and infrastructure developments as by cell-level innovation. Standardization activity is expanding across multiple forums. The International Electrotechnical Commission's Technical Committee 21 has broadened its work to develop unified standards and testing protocols for solid-state battery technologies, including updates to the IEC 62660 series. These efforts matter because harmonized testing and certification pathways will directly influence OEM qualification speed, cross-border market access, and investor confidence in production readiness.
At the national level, China plans to release its first national standard for solid-state EV batteries, defining distinctions among liquid, semi-solid, and all-solid-state packs. This type of classification framework can reset competitive expectations by clarifying which technologies fall into which regulatory categories, influencing both procurement specifications and consumer-facing positioning. In the United States, the Department of Energy's Advanced Materials and Manufacturing Technologies Office has awarded SBIR Phase II funding to multiple small businesses focused on innovative manufacturing of next-generation solid-state batteries, signaling public-sector support for manufacturing process innovation. Preliminary safety testing guidelines are also being established by the Department of Energy and the Consumer Product Safety Commission, even as full standards remain under development.
Infrastructure and raw material dynamics introduce additional strategic considerations. Solid-state batteries consume substantial quantities of solid electrolytes per unit of production capacity, and the scaling of electrolyte manufacturing, precursor sourcing, and specialized production infrastructure represents a material constraint that will shape early gigafactory economics. These supply-side realities interact with roll-to-roll processing requirements, cell stacking precision, and quality control demands to create a set of execution risks that are often underweighted in technology-only assessments. The full study integrates these dynamics into a cohesive view of where friction will emerge and how different developer models are preparing to address it.
All-Solid-State Battery Market
Why This Research Matters for 2026 Strategy
Entering 2026, the all-solid-state battery market is transitioning from narrative-driven anticipation to milestone-driven evaluation. Enterprises that depend on battery technology for product differentiation, cost structure, or sustainability positioning need more than headlines. They need a structured understanding of which technical pathways are reaching pilot readiness, which electrolyte and cell architectures are attracting OEM sampling and licensing interest, where regional manufacturing ecosystems are forming, and how standardization and safety guidelines will alter qualification timelines.
The strategic value of this research lies in its capacity to support concrete decisions. Technology teams can use the segmentation and developer profiling to benchmark internal roadmaps against external milestones. Supply chain and procurement leaders can anticipate electrolyte capacity constraints and manufacturing infrastructure requirements as they plan for scale-up. Corporate development and partnership teams can identify which organizations are moving from demonstration to pilot production, which joint ventures are consolidating electrolyte supply, and which gigafactory collaborations signal near-term commercialization intent. Investors and advisors can use the macro trajectory, competitive mapping, and regulatory watchpoints to calibrate expectations around adoption pacing and market concentration.
Market concentration data included in the study indicates that the top three participants account for a substantial share of the evaluated landscape, while the top five extend that footprint further. This concentration pattern, when read alongside the diversity of development models and the ongoing arrival of new milestones, suggests a market that is simultaneously consolidating around capable players and still open to new entrants with differentiated technical or manufacturing advantages. Understanding where concentration ends and white space remains is one of the decisive questions the report is built to answer.
What You Will Gain From the Full Study
The complete PW Consulting all-solid-state battery market research delivers a decision-grade intelligence package. It connects historical expansion and forward-looking growth projections to the operational realities of electrolyte scaling, cell architecture selection, application qualification cycles, and regional manufacturing development. It profiles active developers with milestone-level tracking, integrates regulatory and standardization developments into commercial timing assessments, and highlights the raw material and infrastructure dynamics that will influence early production economics.
Crucially, the report preserves analytical depth without reducing the market to static divisions. Regional, type-based, and application-based segmentation is presented with the contextual interpretation required for strategy work, allowing readers to understand where demand, manufacturing, and policy pressures intersect. The goal is not simply to enumerate the landscape, but to equip decision-makers with the frameworks needed to prioritize investments, time partnerships, and manage execution risk in a market that is moving quickly from pilot lines to early commercial pathways.
For executives and strategy teams operating in 2026, the window for informed positioning is narrow and valuable. The all-solid-state battery market will not wait for organizations to catch up once production standards crystallize and OEM qualification cycles accelerate. The full research provides the structured intelligence required to act with confidence—translating growth projections, competitive milestones, and regulatory developments into a clear strategic plan. We invite you to access the complete report for the detailed segmentation data, developer profiles, regional deployment analysis, and scenario frameworks that will support your 2026 and beyond planning.
For detailed analysis of this topic, please visit the official page: All-Solid-State Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting BMS Report: Market Hits $13.64B in 2025, Forecasts 15.55% CAGR to $37.51B by 2032
By pmarketresearch, 2026-09-15
Powering the Future: Strategic Intelligence for the Battery Management System Market 2026-2032
Introduction: The Critical Role of BMS in a Decarbonizing World
The global transition toward electrification and renewable energy integration is no longer a speculative forecast; it is an operational reality reshaping industrial landscapes. At the heart of this transformation lies the Battery Management System (BMS), the critical electronic brain that ensures safety, performance, and longevity across lithium-ion and emerging battery chemistries. As enterprises navigate the complexities of 2026, understanding the trajectory of the BMS market is not merely an academic exercise but a strategic imperative.
PW Consulting is pleased to introduce our latest comprehensive market research, designed to equip decision-makers with the granular intelligence required to capitalize on emerging opportunities. This report serves as a definitive guide through the rapidly evolving ecosystem of battery management technologies, offering a clear view of where value is being created and where risks are accumulating. The following insights provide a preview of the strategic depth contained within our full analysis.
Market Trajectory: Scale and Growth Dynamics
The momentum behind the BMS sector is underpinned by robust historical performance and an aggressive growth forecast. Our analysis tracks revenue developments from 2020 through the base year of 2025, establishing a solid foundation for forward-looking projections. In 2020, the global market generated approximately 8.6 billion USD. By 2025, this figure had climbed to 13.64 billion USD, reflecting a compound annual growth trajectory that underscores the accelerating adoption of battery-dependent technologies.
Looking ahead to the forecast period spanning 2026 to 2032, the market is projected to reach 37.51 billion USD. This expansion represents a sustained CAGR of 15.55 percent, signaling that demand drivers are not transient but structural. Such growth rates indicate a market that is maturing yet still expanding rapidly, driven by the dual engines of electric mobility and stationary energy storage. For stakeholders, this trajectory suggests that timing investments correctly will be crucial, as the window to establish competitive positioning before market saturation in certain segments begins to narrow is OPEN.
Building Energy Management System (BEMS) Market
It is important to note that while top-line growth is impressive, the distribution of value across different technological and application layers varies significantly. Our full report dissects these layers to reveal where the highest margins and fastest adoption rates are concentrated, allowing clients to prioritize resources effectively.
Segmentation Insights: Technology, Application, and Regional Nuances
To navigate this market successfully, one must understand the interplay between chemistry types, end-use applications, and geographic dynamics. The report provides a detailed breakdown of the market by technology, distinguishing between Lithium-ion and Lead-acid systems, alongside emerging alternatives. While Lithium-ion continues to dominate due to its energy density and declining cost profiles, specific industrial and legacy applications still rely heavily on established chemistries. Understanding the shifting balance between these types is essential for suppliers manufacturing components or integrators designing systems.
Similarly, the application landscape is diverse. Electric Vehicles (EVs) remain a primary growth vector, but Energy Storage Systems (ESS) and consumer electronics also contribute substantial revenue streams. Each application imposes unique requirements on BMS functionality, ranging from high-current handling in industrial settings to precise communication protocols in solar-plus-storage configurations. Our analysis maps these requirements against current supply capabilities to identify gaps and opportunities.
Geographically, the market exhibits distinct characteristics. While North America and Europe maintain significant shares driven by regulatory mandates and established automotive sectors, the Asia Pacific region represents a massive volume center. Latin America and the Middle East and Africa are emerging as niche but strategically important markets for specific storage and mobility solutions. The full report avoids generic regional summaries, instead providing context on trade flows, local manufacturing capabilities, and regulatory influences that impact market accessibility in each zone.
Competitive Landscape: Key Players and Strategic Moves
The BMS market is characterized by a mix of specialized manufacturers, integrated energy companies, and engineering firms offering custom solutions. Market concentration metrics indicate a CR3 of 25 percent and a CR5 of 35 percent, suggesting that while leading players hold significant influence, the market remains fragmented enough for agile competitors to carve out niches. Success in this environment depends on differentiation through technology, reliability, and ecosystem integration.
Several key companies define the current competitive contours. Daly BMS, based in China, has strengthened its position through continuous product innovation, recently launching a 4th Generation Home Energy Storage BMS with WiFi and Bluetooth connectivity to enhance user monitoring and app integration. Further expanding its ecosystem, Daly announced a new 500W Portable Charger in 2026, demonstrating a strategy to bundle charging solutions with BMS-integrated systems.
In the custom solutions space, Kuruibms has focused on C&I energy storage and EV applications, releasing a market guide in 2026 highlighting top BMS factories to assist buyers in navigating the supply chain. Victron Energy, headquartered in the Netherlands, continues to refine its VE.Bus and Lynx Smart BMS models, updating documentation in early 2026 to ensure compatibility with multiplus inverters and broader energy storage architectures. These updates reflect an industry-wide push toward seamless interoperability between BMS units and inverters.
Battery Management System (BMS) Market
North American and European players are also active. UgoWork in Canada emphasizes safety and fleet deployment by integrating UL 1998 certified BMS with lithium-ion batteries for material handling. Novelic in France designs comprehensive BMS for e-mobility, integrating monitoring and cooling. In Germany, comemso electronics provides critical testing and simulation tools that allow other manufacturers to optimize balancing algorithms, indirectly shaping the quality of BMS deployed in EVs. Meanwhile, Nuvation Engineering and Elithion Inc. in the United States offer custom and embedded BMS solutions for industrial and automotive integration, catering to clients requiring tailored specifications.
Recent industry developments also highlight the importance of ecosystem compatibility. For instance, Sol-Ark issued a battery integration guide in 2026 confirming support for various BMS-equipped storage partners, illustrating how inverter manufacturers are increasingly vetting and aligning with specific BMS providers to reduce integration friction for end users. The full report analyzes these partnerships and product launches to determine which strategic alliances are likely to yield long-term market share gains.
Market Dynamics: Supply Chain, Raw Materials, and Regulatory Pressures
Beyond company profiles and segmentation, the macro-environment plays a decisive role in shaping market outcomes. Raw material volatility remains a key concern for manufacturers and integrators. Spot lithium carbonate prices in China increased from approximately 9,300 USD per ton in January 2025 to 10,300 USD per ton by November 2025, driven by surging energy storage demand and mine disruptions. Similarly, Chinese lithium hydroxide prices rose from roughly 10,300 USD to 11,200 USD per ton over the same period. These movements impact bill-of-materials costs and can compress margins if not managed through strategic sourcing or hedging.
Conversely, the United States saw lithium carbonate annual average prices decline by 31 percent to 9,000 USD per ton in 2025 due to short-term oversupply, though battery-grade prices remain elevated year-over-year. This divergence creates complex arbitrage situations and supply chain decisions for global players. The report examines how these price dynamics influence regional manufacturing strategies and the competitiveness of localized production versus imports.
Regulatory shifts are equally impactful. China's policy of reducing VAT export rebates on lithium-ion batteries, effective from April 1, 2026, prompted a front-loading of production and exports, contributing to price volatility and altering trade flows. In Africa, Zimbabwe imposed a ban on exports of all raw minerals, including lithium concentrate, effective February 2026, further tightening global supply. These regulatory actions underscore the geopolitical risks inherent in the battery supply chain. Our analysis provides scenario planning tools to help clients assess exposure to trade policy changes and raw material restrictions.
Report Contents: Operational Intelligence for Decision Makers
This market research is structured to deliver actionable intelligence rather than abstract data. The full document includes detailed profiles of key companies, analyzing their product portfolios, recent developments, and strategic positioning. We provide a comprehensive segmentation analysis that breaks down revenue and volume by type, application, and region, enabling clients to benchmark their performance against market averages.
The report also features a deep dive into market dynamics, covering drivers, restraints, and opportunities. We examine the impact of raw material price fluctuations, regulatory changes, and technological advancements on market growth. Additionally, the study offers strategic recommendations for various stakeholder groups, including manufacturers, investors, and end-users. These recommendations are grounded in data-driven forecasts and competitive analysis, ensuring that decisions are informed by the latest market realities.
Readers will also find historical data from 2020 to 2025, providing context for current trends, alongside forecast data extending to 2032. This long-term view allows organizations to plan capital expenditures, R&D investments, and market entry strategies with confidence. The inclusion of recent product launches, market guides, and compatibility updates ensures that the analysis reflects the most current state of the industry.
Conclusion: Navigating the Next Wave of Growth
The Battery Management System market stands at a pivotal juncture. With a projected revenue of 37.51 billion USD by 2032 and a CAGR of 15.55 percent, the sector offers substantial opportunities for those who can navigate its complexities. However, success requires more than just observing growth trends; it demands a nuanced understanding of competitive dynamics, supply chain vulnerabilities, and regional regulatory environments.
PW Consulting's comprehensive report provides the depth and clarity needed to make informed strategic decisions. By uncovering hidden patterns in segmentation, evaluating the impact of recent industry developments, and modeling future scenarios, this research empowers organizations to stay ahead of the curve. We invite you to access the full report to gain the complete intelligence picture and leverage these insights for your 2026 planning and beyond. The future of energy storage and electric mobility depends on robust battery management; ensure your strategy is built on the best available data.
For detailed analysis of this topic, please visit the official page: Battery Management System (BMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plasma Sterilizer Market Hits $515M in 2025, Projected 6.1% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Imperative: Navigating the Plasma Sterilizers Market in 2026 and Beyond
The global healthcare infrastructure is undergoing a paradigm shift in infection control protocols, driven by increasing surgical volumes, stringent regulatory frameworks, and the critical need for sterilizing heat-sensitive medical instruments. For executives and strategic planners, understanding the trajectory of the Plasma Sterilizers Market is no longer optional; it is a fundamental component of capital allocation and risk management. This analysis draws from the comprehensive market intelligence provided in our latest research, offering a high-level view of the landscape while underscoring the necessity of granular data for precise decision-making in 2026.
Market Trajectory and Historical Performance
The plasma sterilization sector has demonstrated consistent resilience and growth over the past half-decade. Historical data from 2020 to 2025 indicates a mature yet expanding market, with revenue climbing from 350.0 million USD to 515.0 million USD. This upward trend reflects the steady adoption of low-temperature sterilization technologies in settings where steam autoclaving is ineffective.
Looking toward the forecast period spanning 2026 to 2032, the market is projected to continue its expansion. The compound annual growth rate (CAGR) is estimated at 6.1 percent. By 2032, overall market revenue is anticipated to reach 775.43 million USD. These figures suggest a stable growth environment, though they mask the underlying volatility and opportunity pockets that exist within specific segments. For a business leader, knowing the aggregate number is the starting point; understanding the drivers behind the variance between 2026 and 2032 is where strategic advantage is found.
The 2026 Decision Matrix: Why Deep Intelligence Matters
As organizations plan their operational roadmaps for 2026, relying on top-line market figures is insufficient. The market is characterized by distinct technological preferences, regional disparities, and application-specific demands that aggregate data cannot reveal. The following sections outline the critical dimensions where detailed intelligence transforms vague strategy into actionable execution.
Technological Segmentation and Device Form Factors
The market is divided into distinct product categories, each serving different clinical and operational needs. Floor-standing units represent a significant portion of the market value, catering to large hospitals and central sterilization departments that require high throughput. However, the rise of portable and table-top plasma sterilizers indicates a shifting trend toward point-of-care sterilization and decentralized processing.
Our report dissects these categories to reveal which form factors are gaining traction in specific clinical settings. For procurement managers, the choice between a floor-standing system and a portable unit involves trade-offs regarding capital expenditure, maintenance logistics, and workflow integration. Understanding the revenue split and growth velocity of each type allows organizations to align their procurement strategies with actual utilization rates rather than legacy habits. The data suggests that while larger systems dominate current revenue, the flexibility of smaller units is driving incremental adoption in specialized clinics and veterinary practices.
Application Diversity: Hospitals and Manufacturing
Demand is not monolithic across end-users. Hospitals remain the primary consumers of plasma sterilization technology, driven by the need to process complex surgical instruments and implantable devices. However, the pharmaceutical and medical device manufacturing sectors represent a high-value secondary market. In these environments, sterilization is critical for ensuring product safety and compliance with good manufacturing practices (GMP).
Plasma Sterilizers Market
The research provides a detailed breakdown of how demand is distributed across these applications. For manufacturers, the opportunity lies in integrating sterilization validation into the product development lifecycle. For healthcare providers, the focus is on throughput and compatibility with diverse instrument sets. The report examines the specific revenue contributions of hospitals versus manufacturing sectors, highlighting where the highest margin opportunities and volume demands reside. Ignoring the nuance between these application fields can lead to misaligned product positioning or failed market entry strategies.
Regional Dynamics and Global Distribution
Geography plays a pivotal role in market accessibility and growth potential. While North America has historically maintained a dominant position in terms of revenue generation, other regions are exhibiting evolving maturity levels. Europe holds a substantial share, reflecting strong healthcare infrastructure and regulatory compliance standards. Meanwhile, the Asia Pacific region presents a different growth profile, often characterized by increasing healthcare expenditure and expanding hospital networks.
Latin America and the Middle East and Africa constitute smaller portions of the global revenue base but offer emerging opportunities as healthcare systems modernize. Our analysis avoids generic regional generalizations. Instead, it provides specific insights into which regions are driving volume versus value. For international players, knowing where the revenue is concentrated helps in prioritizing distribution channels and regulatory approvals. For instance, a strategy focused on high-volume, low-cost units might target different regions compared to a strategy focused on premium, high-throughput systems. The full report details the specific revenue magnitudes for each region, enabling a precise geographic prioritization matrix.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with a significant portion of revenue held by leading players. The competition is defined not just by market share but by technological innovation, regulatory clearance, and specific product differentiation. Understanding the moves made by key competitors is essential for anticipating market shifts and identifying gaps in the offering.
Key Market Participants
Several companies define the current competitive landscape, each with distinct strategic focuses:
- Tuttnauer , headquartered in Breda, Netherlands, is known for producing the PlazMax line of low-temperature hydrogen peroxide plasma sterilizers. Their focus remains on instruments that are sensitive to heat and moisture, positioning their technology as a reliable solution for general medical instrument sterilization.
- Advanced Sterilization Products (ASP) , based in Irvine, California, continues to be a pivotal player with its STERRAD 100NX Sterilizer featuring ALLClear Technology. This platform is widely recognized for low-temperature hydrogen peroxide gas plasma sterilization.
- Plasmapp , from Seoul, South Korea, markets the STERLINK medical cryo plasma sterilizer. With FDA clearance for units under 20 L capacity, they target specific niches requiring compact, low-temperature sterilization solutions.
- Steris Corporation , located in Warrendale, Pennsylvania, offers V-PRO low-temperature plasma sterilization systems. Their portfolio is heavily integrated into the broader medical device and hospital sterilization ecosystem.
- VetOvation , operating in the United States, provides Sterlink gas plasma sterilizers specifically tailored for veterinary hospital applications, highlighting a specialized vertical within the broader market.
Recent Developments and Regulatory Shifts
The competitive environment is dynamically influenced by regulatory clearances and technological updates. In April 2025, Advanced Sterilization Products Inc. received FDA 510(k) Clearance for the STERRAD 100NX Sterilizer with ALLClear Technology (K250802). This clearance validates the use of hydrogen peroxide gas plasma sterilization for a broad range of medical instruments, reinforcing the platform's compliance standing.
Furthermore, in August 2024, ASP collaborated with PENTAX Medical to secure FDA clearance for the ULTRA GI Cycle. This cycle is designed for use in the STERRAD 100NX Sterilizer with ALLClear Technology specifically for duodenoscope reprocessing. This development underscores the importance of specialized cycles for complex devices like duodenoscopes, where infection control is critical. Similarly, PENTAX Medical received FDA clearance in August 2024 for the DEC Duodenoscope, which is compatible with the STERRAD 100NX Sterilizer plasma technology.
These events highlight a trend where regulatory approval is not just a one-time hurdle but an ongoing process of expanding indications and compatible device portfolios. For competitors and investors, tracking these clearances is vital for assessing the longevity and scope of competing platforms.
Regulatory and Reimbursement Dynamics
The operating environment for plasma sterilizers is heavily influenced by regulatory standards and institutional reimbursements. Recognition by major health bodies provides the foundational trust required for adoption. Hydrogen peroxide gas plasma sterilizers are recognized by the CDC and FDA as Established Category A low-temperature sterilization processes. This classification confirms their compatibility with heat- and moisture-sensitive medical devices, providing a regulatory seal of approval that drives procurement in regulated healthcare environments.
Additionally, the standardization of validation processes is tightening. The FDA has recognized ISO 22441:2022 as the standard for low-temperature vaporized hydrogen peroxide sterilization validation and routine control. Compliance with this standard is becoming a baseline expectation for manufacturers and users alike. Our report analyzes how these regulatory benchmarks impact market entry barriers and operational costs. Organizations must ensure their sterilization protocols align with these evolving standards to avoid compliance risks. The full intelligence provided in the study details how these regulations influence regional adoption rates and product design requirements.
Desktop Plasma Cleaner Market
Strategic Outlook for 2026
As the market moves through the forecast period, the convergence of technological maturity, regulatory enforcement, and healthcare expansion will define the growth trajectory. The projected revenue growth from 563.22 million USD in 2026 to 775.43 million USD in 2032 indicates a robust market potential. However, capturing this value requires more than observing the growth curve.
Strategic decisions in 2026 will hinge on understanding the interplay between product types, application needs, and regional readiness. For instance, the concentration of market share among top players suggests that partnership or niche specialization may be necessary for new entrants. The specific revenue contributions of regions like North America versus Asia Pacific will dictate where capital should be deployed for maximum return. Similarly, the divergence between hospital-based demand and manufacturing requirements necessitates tailored value propositions.
This overview provides a foundational understanding of the Plasma Sterilizers Market landscape. However, the true utility for strategic planning lies in the granular details that drive these aggregates. The exact revenue splits, the precise CAGR variations across segments, and the detailed competitive profiling contained in the full report are essential for building a resilient strategy.
To access the complete dataset, including specific regional revenue figures, detailed segmentation splits, and comprehensive company profiles with recent strategic developments, we invite you to secure the full market research report. In a market defined by 6.1 percent CAGR and evolving regulatory standards, the difference between average performance and market leadership often lies in the depth of intelligence available to decision-makers.
For detailed analysis of this topic, please visit the official page: Plasma Sterilizers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Looking for an engaging online slot experience? Pussy888 Slot Game brings together a selection of entertaining slot titles with attractive themes, smooth interfaces, and mobile-friendly gameplay. Players can explore different reel formats, game styles, and exciting features in one convenient platform. With easy navigation and a broad range of options, Pussy888 makes it simple to discover your favorite slot games and enjoy online casino entertainment responsibly.
PW Consulting: Refrigerated Display Cases Market Hits $9.83 Billion in 2025, Projects 7.4% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence in the Cold Chain: Navigating the Refrigerated Display Cases Market Outlook 2026–2032
Executive Summary: The Imperative for Data-Driven Decision Making
The global refrigeration landscape is undergoing a structural transformation driven by tightening environmental regulations, evolving consumer expectations for product visibility, and relentless pressure on operational energy costs. For stakeholders across retail, foodservice, and commercial refrigeration, the Refrigerated Display Cases Market represents a critical nexus of capital expenditure, compliance risk, and revenue generation. PW Consulting has synthesized a comprehensive market research study spanning the historical trajectory from 2020 through 2025 and projecting forward to 2032. This analysis delivers the strategic intelligence required to navigate the complexities of the 2026 market environment and beyond. The research is designed not merely as a static snapshot, but as a dynamic planning tool that equips executives, procurement leaders, and investors with the granular insights necessary to allocate capital efficiently and hedge against systemic volatility.
Macro Trajectory and Revenue Projections
Understanding the overarching revenue trajectory is the first step in framing strategic investments. Over the historical review period, the market demonstrated consistent expansion, rising from a baseline of 6,865.0 million USD in 2020 to 9,830.0 million USD by 2025. This upward momentum is projected to continue, with the market valuation expected to reach 10,331.18 million USD in 2026 and accelerate toward 16,140.0 million USD by the end of the forecast period in 2032. The analysis indicates a robust compound annual growth rate of 7.4 percent over the 2026 to 2032 forecast window. This macroeconomic expansion is underpinned by widespread modernization initiatives in grocery and convenience sectors, alongside mandatory upgrades triggered by regulatory shifts. However, aggregate figures only tell part of the story. The true strategic advantage lies in dissecting the velocity of growth across different technological architectures, application verticals, and geographic corridors, each of which presents distinct risk-return profiles for market participants.
Core Report Architecture and Actionable Intelligence
The complete research study is structured to provide end-to-end visibility into the market ecosystem, enabling stakeholders to build resilient business strategies. The report delivers a multi-dimensional analysis that moves beyond surface-level observations to uncover the operational and financial drivers shaping the industry. Key components include:
- Comprehensive profiling of market segmentation by product architecture, covering plug-in, remote, and semi-plug-in configurations, with detailed assessments of their respective adoption curves and total cost of ownership implications.
- Deep-dive evaluation of application verticals, examining how demand dynamics diverge between food service operations and retail food and beverage environments, including channel-specific purchasing behaviors and capacity utilization metrics.
- Regional market mapping that quantifies demand intensity, infrastructure readiness, and competitive saturation levels across major economic zones, providing a framework for prioritizing market entry or expansion initiatives.
- Supply chain and raw material analysis that tracks pricing volatility, component availability, and manufacturing constraints affecting critical inputs such as tempered glass, stainless steel, and aluminum, alongside mitigation strategies for procurement teams.
- Regulatory impact modeling that quantifies the financial and operational consequences of compliance mandates, including refrigerant charge limits, energy efficiency certification requirements, and phase-out timelines for legacy technologies.
- Competitive benchmarking and strategic grouping of market participants based on product portfolios, geographic footprints, innovation pipelines, and corporate development trajectories.
This structured approach ensures that decision-makers can align technology selection, capital deployment, and partnership strategies with the specific growth vectors and constraint boundaries that define the current market cycle.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderately concentrated competitive environment, with the top three participants collectively commanding approximately 48.0 percent of total revenue and the leading five firms accounting for 57.0 percent. This concentration reflects the high barriers to entry associated with engineering certification, distribution network development, and compliance with stringent energy and environmental standards. The competitive field features a mix of established multinational manufacturers and specialized regional players, each pursuing distinct value propositions to differentiate their offerings.
In North America, prominent players such as Hussmann Corporation from Chicago, Carrier Commercial Refrigeration based in Syracuse, Zero Zone Inc. from Madison, True Manufacturing Co. Inc. in Saint Augustine, Hillphoenix Inc. in Fort Worth, and Kysor Warren in Dallas maintain strong market positions through expansive product lines and direct service networks. Hussmann, for instance, has built its reputation on a comprehensive lineup of multi-deck, island, and reach-in merchandisers that integrate natural refrigerants, energy-efficient lighting, and customizable configurations tailored to retail and foodservice environments. Carrier Commercial Refrigeration emphasizes integrated store systems and display cases featuring both plug-in and remote solutions, with a strong focus on low-GWP refrigerants and smart control architectures that enable centralized monitoring and optimization. Zero Zone Inc. offers a suite of series including Crystal, Highlight, Guardian, and Reveal, alongside its Hybrid and ultra-narrow models engineered for energy efficiency and space optimization in constrained retail footprints. True Manufacturing Co. Inc. focuses on reach-in coolers, glass-door merchandisers, and display cases that prioritize durability, LED lighting integration, and energy performance across both foodservice and retail applications. Hillphoenix Inc. has positioned itself at the forefront of sustainable refrigeration with its AdvansorFlex CO2 and SoloChill series, which are optimized for energy efficiency, serviceability, and transcritical system performance. Kysor Warren contributes specialized refrigerated merchandisers engineered for durability, reliability, and labor savings in supermarket and retail settings.
European manufacturers bring distinct engineering philosophies and regulatory compliance expertise to the global market. Epta S.p.A., headquartered in Vimercate, Italy, delivers the Zenith and Costan lines of vertical and multi-deck refrigerated cabinets, achieving up to 36 percent energy savings through natural refrigerants and PFAS-free insulation, with EU Energy Class B certification. Arneg S.p.A., based in Bologna, emphasizes modular and plug-in refrigerated cabinets with a strong emphasis on sustainable refrigeration and custom store design solutions that adapt to varied retail formats. AHT Cooling Systems GmbH from Austria offers the BOREA and plug-in multideck refrigerated cases utilizing natural refrigerants such as R290, targeting retail outlets and convenience stores with compact, efficient configurations. In the Asia-Pacific region, Hoshizaki Corporation in Nagoya, Japan, provides reliable refrigerated display cases with a focus on convenience store and foodservice segments, emphasizing durability and energy performance. Frigoglass S.A.I.C., based in Athens, Greece, supplies glass-door coolers and refrigerated cabinets tailored for beverage and food display, supported by an international distribution network that extends its reach across multiple continents.
Refrigerated Display Cases Market
Recent Industry Movements and Innovation Signals
Recent corporate activities underscore the pace of technological advancement and the strategic importance of product innovation in capturing market share. In September 2025, Hussmann Corporation launched the RLN-A and RMN-A reach-in merchandisers, incorporating Air-Cooled Microblock technology designed to improve product temperature retention and enhance energy efficiency. This launch reflects a broader industry trend toward thermal management optimizations that directly impact both compliance standing and operating cost structures. In July 2025, Epta S.p.A. showcased the MD3 double-sided multideck cabinet at Metcash 2025, a configuration offering up to 30 percent floor space reduction for independent retail stores. Such space-saving innovations address the persistent challenge of maximizing merchandising density without compromising cooling performance or customer accessibility. In April 2025, Hillphoenix Inc. introduced ChargeSecure technology for CO2 refrigeration systems, delivering 1.5 amps operation and consuming six times less energy than conventional units. These developments highlight the competitive advantage accruing to manufacturers that can simultaneously address energy efficiency, refrigerant compliance, and operational reliability. Stakeholders who track these innovation cycles gain early visibility into emerging product standards and can align their procurement or development roadmaps accordingly.
Regulatory Pressures and Material Constraints Shaping Market Dynamics
The 2026 market environment is being reshaped by a confluence of regulatory mandates and material supply dynamics that demand proactive strategic adaptation. Starting January 1, 2026, new installations of Hybrid merchandisers are prohibited under the AIM Act, requiring replacement with low-GWP refrigerant alternatives. This regulatory shift, coupled with low-GWP refrigerant requirements under the AIM Act that limit refrigerant charge to 200 pounds for new installations, is driving accelerated adoption of R-290 and CO2 systems in display cases. These constraints are not merely compliance checkboxes; they fundamentally alter the economics of product selection, installation logistics, and long-term service contracts.
In parallel, EU Energy Class B certification mandates for vertical refrigerated cabinets are compelling manufacturers and end-users to prioritize high-efficiency designs. Epta's Zenith line, achieving up to 36 percent energy savings through natural refrigerants and PFAS-free insulation, exemplifies the performance benchmarks now required to meet these standards. On the materials front, glass doors dominate refrigerated display cases, with tempered safety glass capturing approximately 38.7 percent market share due to its optical clarity and hygiene compliance. Stainless steel and aluminum remain primary structural materials, and while component costs including steel, aluminum, and glass showed moderated price volatility in 2025, persistent supply chain risks continue to warrant careful inventory planning and supplier diversification. These regulatory and material factors interact to create a complex decision matrix where energy performance, compliance timelines, and input cost stability must be evaluated in concert.
Strategic Implications for 2026 and the Path Forward
The refrigerated display cases market in 2026 presents a landscape where growth is accessible but competition for share is intensifying, and where regulatory compliance is no longer a peripheral concern but a central pillar of product strategy. Organizations that succeed in this environment will be those that integrate macro demand signals with micro-level insights into product architectures, regional adoption patterns, and competitive maneuvering. The full study provides the detailed segmentation data, regional revenue breakdowns, application-specific growth rates, and competitor benchmarking matrices necessary to construct precise market entry strategies, optimize portfolio mixes, and anticipate regulatory-driven demand shifts. Readers seeking to unlock the complete dataset and proprietary analytical frameworks are encouraged to access the source research portal, where the full report delivers the granular intelligence required to inform capital allocation, technology roadmapping, and long-term competitive positioning.
Worldwide Home Display Case Market
For detailed analysis of this topic, please visit the official page: Refrigerated Display Cases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Basmati Rice Market to Hit $315.1M by 2032, Growing at 6.98% CAGR
By pmarketresearch, 2026-09-15
Strategic Horizons: Navigating the Global Basmati Rice Market in 2026 and Beyond
Executive Summary: The Imperative for Precision Intelligence
The global basmati rice sector stands at a critical juncture where traditional trade flows intersect with shifting regulatory frameworks, evolving consumer preferences, and strategic realignment among key producing nations. For executives, procurement leaders, and market strategists operating in 2026, relying on retrospective summaries or anecdotal trade intelligence is no longer sufficient. The market is characterized by compounding macroeconomic pressures, fragmented supply chains, and highly asymmetric information flows across regions. Our latest basmati rice market research was designed to close that gap.
Prepared as a comprehensive analytical foundation rather than a superficial industry overview, this report translates multi-year historical performance and forward-looking model trajectories into actionable strategic intelligence. It is engineered to support pricing architecture, sourcing diversification, capacity planning, export positioning, and risk mitigation across the entire basmati value chain. The following sections outline the analytical rigor, structural frameworks, and decision-ready content embedded within the study, demonstrating why it serves as a critical reference point for enterprise strategy in the current operating environment.
Market Trajectory and Structural Momentum
Historical baselines spanning 2020 through 2025 reveal a market that has absorbed external disruptions, adapted to shifting demand patterns, and consistently expanded its revenue footprint. Over this period, the global basmati rice market progressed from approximately $147.5 million to $198.0 million, reflecting sustained growth driven by expanding consumer adoption, strengthening trade linkages, and product standardization across major export corridors. This historical momentum establishes a reliable baseline for evaluating forward performance.
The forward trajectory extends through 2032, projecting continuous expansion with a compound annual growth rate of 6.98 percent. Under this modeled pathway, market revenue scales from an estimated $205.89 million in 2026 to over $315.1 million by 2032. These figures represent aggregate market evolution rather than isolated product or channel spikes, indicating that underlying demand drivers are structural rather than cyclical. Importantly, this growth is unevenly distributed across geographies and product formats, meaning that generalized assumptions can misallocate capital or expose firms to avoidable margin compression.
Because growth is not uniform, decision-makers require granular visibility into where value is concentrating, which formats are driving incremental dollar share, and how regional demand elasticity interacts with trade policy shifts. The report addresses this complexity by mapping historical inflection points, identifying the mechanisms behind period-over-period revenue shifts, and situating forward projections within established market architecture. The objective is to enable firms to distinguish between durable expansion and temporary arbitrage opportunities, ensuring that investment and sourcing commitments align with long-term structural realities rather than short-term headline noise.
Report Architecture: Operational Content for Execution Teams
A market study only delivers value when it translates into executable direction. Accordingly, this publication was structured around operational deliverables that procurement, commercial, and strategy teams can integrate directly into planning cycles. The analytical architecture moves from macro validation to segment-level mechanics, then to competitive and regulatory overlays, ensuring that every conclusion is traceable to methodologically consistent inputs.
Core components include a full historical reconstruction from 2020 through 2025, with period-over-period revenue movements contextualized against demand shifts, pricing behavior, and trade flow adjustments. The forward modeling covers 2026 through 2032 and is built on scenario-sensitive assumptions, allowing leadership to test sensitivity around volume growth, price realization, and policy-induced supply changes. Rather than presenting a single deterministic path, the study incorporates structural variability so that organizations can evaluate performance under differing operating conditions.
The segmentation framework examines the market through format distinctions, demand-end utilization patterns, and regional allocation trends. These dimensions are deliberately analyzed in combination because basmati rice performance cannot be understood through a single lens. Format shifts influence processing requirements and pricing tiers. Demand-channel dynamics shape inventory velocity, promotional strategy, and margin structure. Regional performance reflects trade agreements, tariff exposure, logistical constraints, and consumer preference evolution. By treating segmentation as an interconnected system, the report enables readers to identify which combinations are generating disproportionate value and where realignment may be necessary.
Another critical layer is competitive and institutional mapping. The study profiles the organizations shaping production, export coordination, trade facilitation, and downstream brand positioning. It does not limit analysis to product attributes; it also evaluates how trade bodies, industry associations, and export federations influence market access, policy advocacy, certification environments, and negotiating leverage. This institutional dimension is especially relevant in agricultural commodity markets, where collective representation and government-aligned export frameworks can alter competitive outcomes as significantly as individual firm strategy.
Basmati Rice Market
Finally, the regulatory and macro context is integrated throughout rather than isolated as a standalone appendix. Trade restrictions, tariff adjustments, floor price mechanisms, certification requirements, and supplier registration processes are analyzed for their direct impact on cost structures, shipment timing, and market-entry feasibility. This ensures that strategic recommendations are grounded in operational reality, not abstract market sizing.
Competitive Architecture and Institutional Dynamics
The basmati rice ecosystem is shaped by a mix of commercial producers, export associations, and institutional research bodies, each exerting influence over pricing, quality standards, supply reliability, and market access. Understanding this architecture is essential for firms seeking to navigate sourcing decisions, brand positioning, and regional expansion strategies.
Among commercial brand actors, RiceSelect operates as an active US-based producer offering Texmati White Rice, a hybrid basmati-style aromatic long-grain product developed through previous RiceTec lineage. The company emphasizes non-GMO, gluten-free, and Kosher-certified positioning while expanding sustainable lines that include Premium Indian Basmati Rice. For downstream distributors and retail partners, this profile signals a strategy that blends American-market familiarity with international basmati credentials, emphasizing certification, product consistency, and sustainability messaging as differentiators. The strategic implication is not merely product availability but brand architecture: firms entering or expanding in the US market must contend with players that are actively bridging origin credibility with domestic retail expectations.
On the export coordination side, the Rice Exporters Association of Pakistan (REAP) serves as a central institutional vehicle for Pakistani basmati rice exporters. Its function extends beyond membership administration to include trade delegation facilitation, global market promotion, and direct engagement with overseas buyers. Recent US engagement activities illustrate how producer-country associations increasingly act as coordinated market-access platforms, helping align exporter interests with foreign distributor expectations. In a market where origin perception, pricing competitiveness, and compliance readiness all influence purchasing decisions, such institutional coordination can materially affect the speed and scale at which supplying countries expand footprint.
The India Rice Exporters Federation (IREF), based in New Delhi, operates as an apex trade body representing Indian rice exporters. It supports basmati producers and facilitates policy advocacy directed at export-oriented production and trade. Given the scale and global prominence of Indian basmati shipments, IREF’s advocacy and coordination role influences how exporters interpret regulatory shifts, manage certification obligations, and respond to policy recalibration. In practical terms, these institutions function as information and negotiation hubs, shaping how producer-country supply responds to international price signals and import-country trade rules.
Competitive understanding also requires situational awareness of recent high-visibility events that expose operational vulnerabilities and accelerate structural adjustments. A voluntary recall involving Kirkland Signature Traditional Basmati Rice in the US retail environment underscores the sensitivity of consumer-facing supply chains to quality assurance failures. Even when isolated, incidents of this nature affect retailer confidence, audit expectations, and supplier qualification standards. For sourcing teams, the lesson is not simply risk avoidance but the need for rigorous traceability, batch control, and supplier compliance documentation across the basmati supply chain.
Equally relevant is the institutional push toward input efficiency and cultivation modernization. The launch of new RobiNOweed Basmati Rice varieties developed for direct seeded rice cultivation reflects an industry-level response to resource constraints, particularly water usage. Varieties designed for DSR systems can alter production economics, yield stability, and regional planting patterns. For buyers and analysts, such developments signal potential shifts in supply-side cost structures and long-term agronomic conditions, especially in producing regions where water availability and labor economics remain pressing considerations.
Regulatory and Trade Realignment: Mapping Systemic Risk
Trade policy and regulatory design have become central determinants of basmati rice competitiveness. In 2026, market participants cannot evaluate sourcing or export strategy without accounting for tariff asymmetry, floor price changes, export restriction cycles, and registration frameworks that govern shipment eligibility.
A significant competitive shift emerged from tariff divergence affecting US import dynamics. The imposition of a 50 percent tariff on Indian basmati rice imports raised effective landed costs and altered relative price positioning in the American market. This development created conditions in which Pakistani basmati rice, subject to a lower tariff rate, gained renewed competitiveness. The strategic consequence is not a simple swap of origin preference; it is a recalibration of price-sensitive procurement, brand positioning, and distributor negotiation leverage. Firms that fail to incorporate tariff-adjusted landed cost modeling into sourcing decisions risk mispricing, margin erosion, or suboptimal supplier allocation.
Regulatory recalibration in the producing country context further complicates planning. India’s policy actions included the lifting of export restrictions on non-basmati white rice alongside the removal of the basmati minimum export floor price, changing the incentive structure for exporters and downstream traders. These adjustments influence shipment timing, export willingness, and downstream pricing expectations across the broader rice trade architecture. Even when a firm’s focus is basmati specifically, non-basmati policy moves matter because they affect total export capacity, logistics utilization, and the strategic behavior of exporters who manage multiple product categories simultaneously.
At the same time, institutional registration and allocation mechanisms remain critical for market participation. APEDA’s issuance of a substantial volume of registration cum allocation certificates for Indian basmati rice exporters during the 2024-25 fiscal year demonstrates the continued role of formalized export authorization in governing shipment eligibility and trade transparency. For international buyers and distributors, the existence of structured registration systems reinforces the importance of verifying exporter status, allocation compliance, and documentation readiness before committing to supply agreements.
Pakistan’s ongoing efforts to expand US market presence also highlight the strategic importance of distributor engagement, pricing alignment, and compliance readiness. Trade discussions involving US distributors reflect a deliberate push to secure market access through commercial and regulatory coordination. In practice, this means that competitive advantage in target markets increasingly depends on a supplier’s ability to demonstrate consistent quality, price competitiveness under tariff conditions, and adherence to buyer-specific compliance expectations.
Procurement, Pricing, and Expansion Strategy in 2026
For enterprise decision-makers, the strategic question is not whether the basmati rice market is expanding, but how to position operations to capture value without overexposing the organization to compliance, pricing, or supply continuity risk. This requires a disciplined approach to sourcing architecture, pricing strategy, and market-entry planning.
Sourcing diversification should be evaluated through the lens of landed-cost realism rather than origin branding alone. Tariff differentials, logistics reliability, certification requirements, and supplier compliance maturity all influence effective cost. Firms that maintain concentration in a single origin or a narrow supplier base may find themselves vulnerable to policy shifts or trade-flow disruptions. A more resilient approach involves mapping multiple qualified sources, stress-testing scenarios against tariff and floor-price changes, and aligning supplier selection with specified audit and documentation expectations.
Pricing architecture must account for volatility in both input markets and trade policy. Floor price changes, tariff adjustments, and recall-driven quality reassessments can alter the price environment faster than traditional seasonal forecasting anticipates. Organizations should incorporate scenario-based pricing models that include tariff-adjusted comparisons, compliance cost assumptions, and quality-assurance overhead. This helps prevent margin compression when external conditions shift unexpectedly.
Market expansion planning should be equally disciplined. Regional demand patterns differ materially in terms of channel structure, price sensitivity, and certification expectations. Retail and household demand typically favors consistent quality, packaging reliability, and brand trust, while foodservice and hospitality channels emphasize volume consistency, specification adherence, and operational reliability. Understanding which demand environment a firm is entering allows more precise commercial execution and reduces the risk of misaligned positioning.
Quality assurance and traceability also deserve elevated strategic priority. High-visibility quality incidents in consumer-facing channels demonstrate that retailer confidence can be fragile. Supplier qualification processes should therefore go beyond basic product specifications to include traceability systems, batch control discipline, documentation completeness, and audit responsiveness. In a market where brand reputation and retailer trust are closely tied to supply integrity, these capabilities can function as competitive differentiators.
Organic Rice Market
Finally, developments in cultivation technology and resource efficiency should be monitored as longer-term supply-side indicators. Agronomic shifts that reduce water usage or improve direct seeding viability can influence regional production economics and supply stability over time. While these changes may not translate immediately into short-term pricing moves, they are relevant to medium- and long-term sourcing strategy, especially for organizations with multi-year supply commitments or regional expansion targets.
Why the Full Study Matters for Executive Decision-Making
The basmati rice market presents a paradox that many organizations underestimate: the headline trajectory is strong, but the operational levers that determine success are highly specific. Aggregate growth figures and broad regional performance indicate favorable conditions, yet they do not reveal which formats are generating disproportionate revenue, which channels are most sensitive to price or certification shifts, or how tariff and policy divergence is reshaping competitiveness in key import markets. Without segment-level clarity, firms risk making allocation, pricing, and sourcing decisions on incomplete pictures.
This report is built to resolve that ambiguity. It connects historical performance with forward modeling, embeds segmentation analysis within the broader market architecture, and overlays competitive and regulatory dynamics so that decision-makers can see not only where the market is heading, but also what actions are required to respond effectively. The objective is to provide a defensible analytical foundation for procurement strategy, commercial planning, brand positioning, and risk management.
Organizations that rely on partial information may identify opportunities, but they often misjudge the cost of pursuing them. In contrast, teams equipped with structured segment insights, scenario sensitivity, institutional mapping, and regulatory context can allocate resources more precisely, negotiate with greater confidence, and anticipate competition more effectively. That is the strategic value the full study is designed to deliver.
To obtain the detailed segmentations, scenario-based projections, competitive profiles, and operational frameworks referenced throughout this overview, access the complete Basmati Rice Market research on the PW Consulting portal. The full intelligence set is structured for immediate integration into enterprise planning workflows and is intended to support decision-making with the level of specificity required for 2026 strategy execution.
For detailed analysis of this topic, please visit the official page: Basmati Rice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com